Expanding investment incentive mechanisms for tourism development.
The resolution comprises 14 articles, stipulating mechanisms and policies for incentives and support for tourism development; support for businesses and community linkages; encouragement of new business models; controlled testing of certain tourism activities; human resource development; facilitation of visas, entry, residence, and allocation of budget resources.
This is an important step in concretizing Resolution No. 26-NQ/TW dated August 22, 2026, of the Politburo on developing Vietnamese tourism into a key economic sector in the new era.
The National Assembly 's resolution establishes a system of specific mechanisms and policies across many fields, ranging from investment incentives, taxes, land, and infrastructure development to business support, business model innovation, human resource development, and facilitating international visitors.
Notably, the policies are designed to be focused and targeted, classifying projects by scale and level of contribution, linking incentives with socio-economic effectiveness, the ability to attract tourists, create jobs, improve product quality, and protect the environment.

The resolution, effective from January 1, 2027, to December 31, 2036, creates a long-term policy framework for localities and businesses to proactively develop investment and tourism development plans.
The resolution defines the policy's scope of application nationwide, prioritizing three growth poles: Hanoi , Ho Chi Minh City, and Da Nang; national tourism centers and areas with potential for national tourism development; and areas developing community-based tourism in ethnic minority regions, mountainous areas, border areas, islands, rural areas, and areas with difficult or extremely difficult socio-economic conditions.
Notably, the Resolution categorizes tourism projects into four groups to apply appropriate preferential policies and support, including: small and medium-sized tourism projects; high-quality tourism projects; dynamic tourism projects; and strategically important dynamic tourism projects.
To encourage investment, the Resolution stipulates the piloting of several preferential tax and land policies for a period of 5 years from the effective date.
The tourism development project is subject to a preferential corporate income tax rate of at least 10% for a period of 5 years on income from tourism-related activities, and is also exempt from or entitled to reductions in land rent as stipulated by the Government.
For strategically important tourism projects, the operating period of tourism components can be up to 70 years; businesses are exempt from corporate income tax for a maximum of 4 years and receive a 50% reduction in tax payable for a period not exceeding 9 years thereafter.
For projects with their entire implementation area located in economically and socially disadvantaged or extremely disadvantaged areas, the Resolution stipulates lower investment capital thresholds and labor requirements compared to other areas, creating conditions to attract investment to regions with great potential but limited resources.

Diversifying the drivers of tourism growth.
The resolution provides numerous policies to support small and medium-sized enterprises, cooperatives, business households, and local communities. Projects must ensure that local communities participate in organizing, managing, and supplying products, and benefit from tourism activities.
Another notable policy is the pilot program to reduce land rent by up to 30% for a period of 5 years for landscape areas, green spaces, water bodies, and common areas not directly used for business purposes by 4-star or higher-rated resort hotels in tourism centers and national tourist areas with a total building density of less than 25%, provided that all specified conditions are met.
The resolution also stipulates policies to support airlines and travel businesses in opening new routes or restoring routes that have been discontinued to bring tourists to the locality. The provincial People's Council decides on the conditions and levels of support in accordance with the budget balance.

Organizations, travel businesses, and accommodation establishments with long-term contracts for purchasing and consuming products under the One Commune One Product (OCOP) program will also be considered for support according to local regulations.
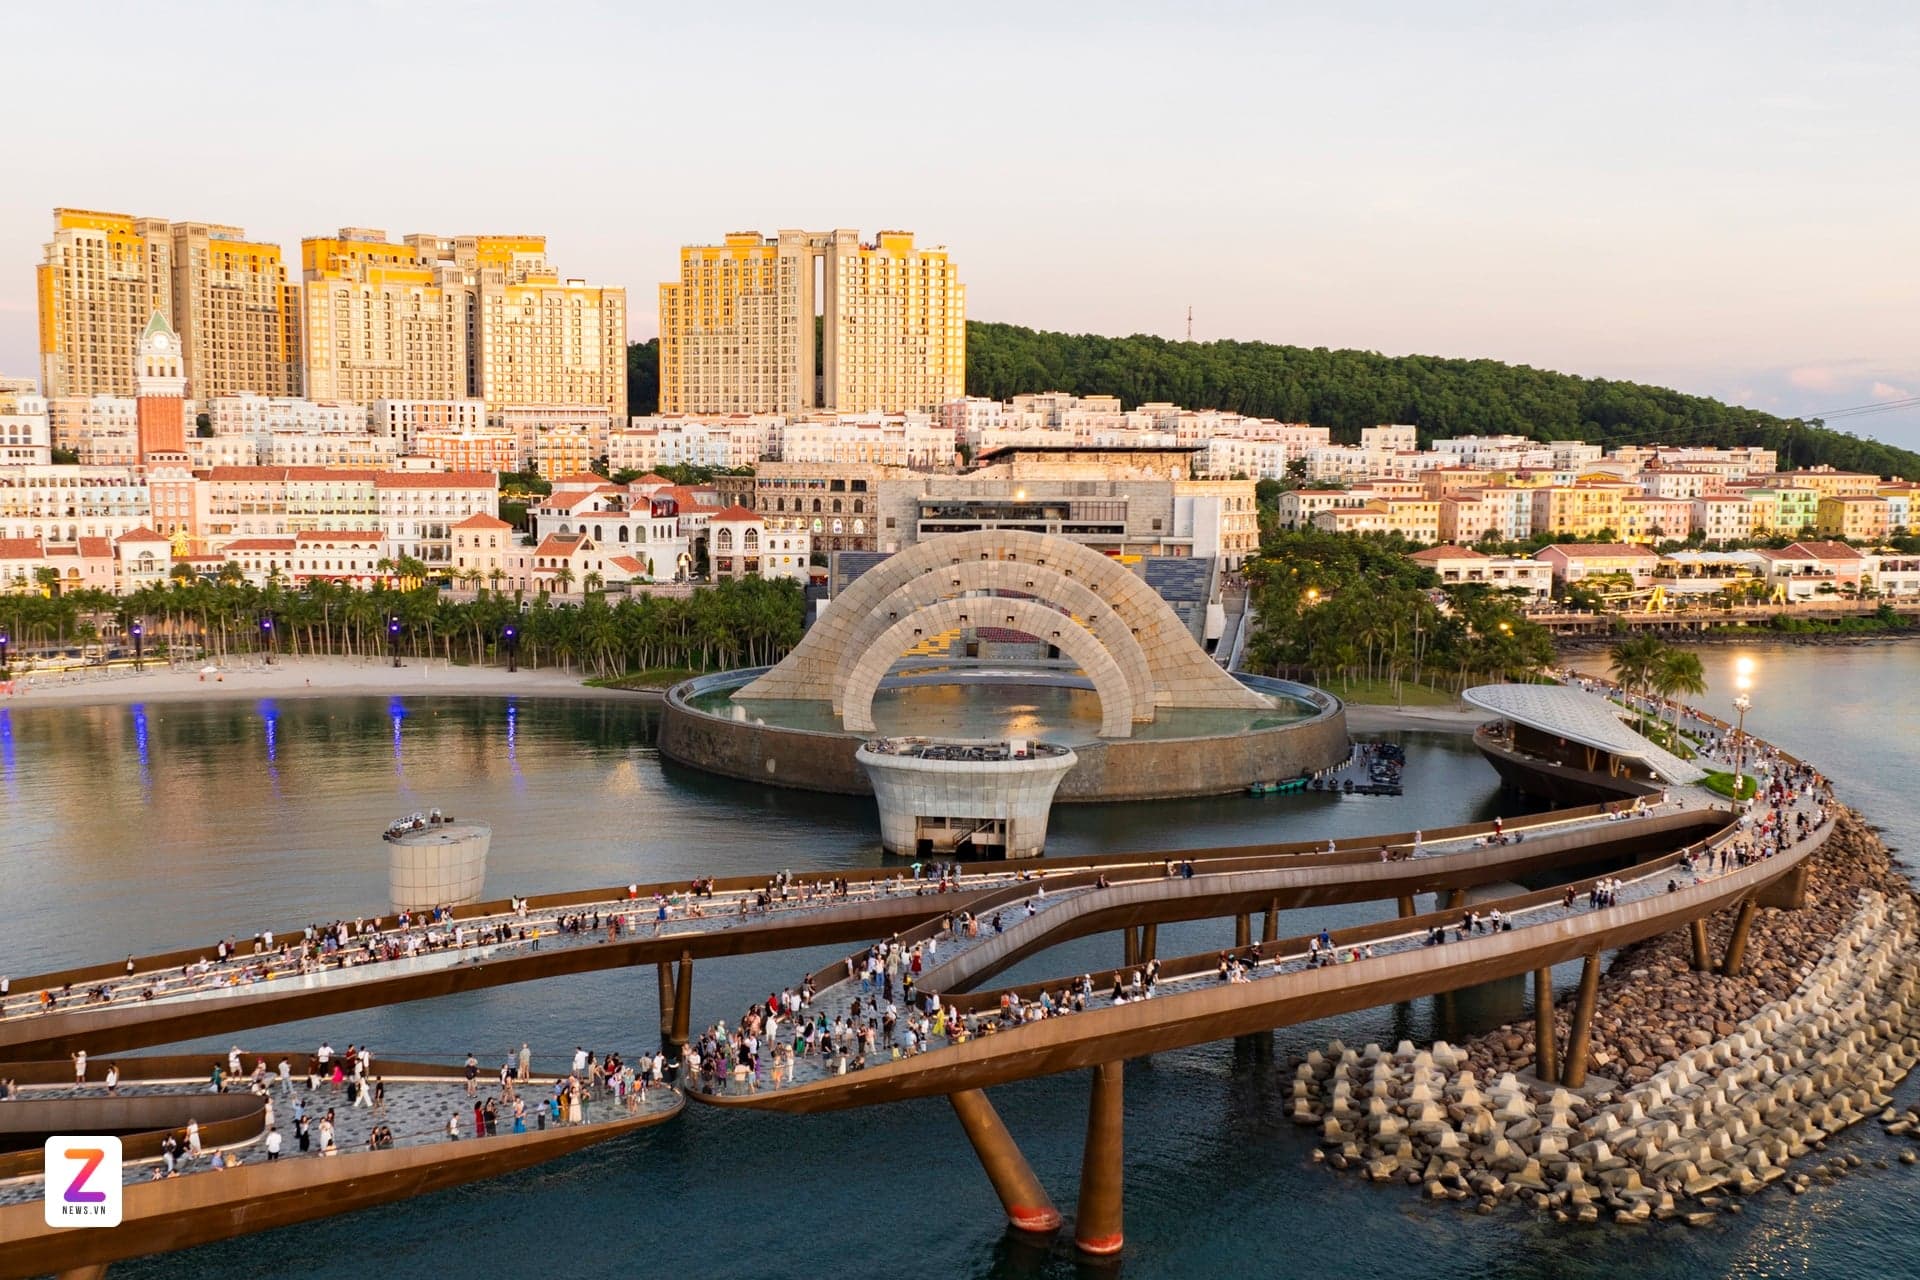
Specifically, the Resolution opens up preferential mechanisms for new tourism business models such as the sharing economy, digital platform businesses, 24/7 integrated tourism, riverside and coastal tourism, and products combining entertainment, culture, sports, and healthcare; models applying artificial intelligence, virtual reality, augmented reality, and new technologies that meet criteria for added value, market expansion, or enhancing the competitiveness of Vietnamese tourism, are exempt from corporate income tax for 2 years and receive a 50% reduction in tax payable for the following 4 years on income from these new business models.
To more effectively exploit tourism potential and increase tourist spending, the Resolution stipulates a controlled pilot mechanism for certain new business models and activities. Performing arts complexes, concert centers, festival streets, and large-scale integrated entertainment areas will be piloted to operate 24 hours a day, 7 days a week.
Large-scale, regularly scheduled or long-term international art performances and events will be subject to streamlined administrative procedures, with a single licensing process through a single point of contact and a single assessment. The pilot program will be implemented based on a plan developed by the provincial People's Committee and submitted to the provincial People's Council for approval.